Category «Seminars»

QFinLab Seminar – Leonardo Baggiani (University of Warwick)

 november 2, 2026
Tuesday, 10 November 2026, 12.45-13.45. Seminar room, third floor, building 14, Via Bonardi 9, Milano (Leonardo Campus); online (Microsoft Teams), https://tinyurl.com/ya3j3ks6 . Leonardo Baggiani (University of Warwick) Title:The Interplay between Utility and Risk in Portfolio Selection. Abstract: In this talk we revisit the problem of portfolio selection, where an investor maximizes utility subject to a …
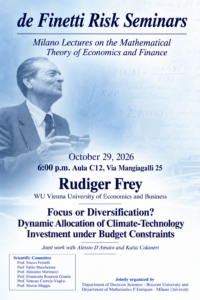
de Finetti seminar: Rudiger Frey – October 29, 2026

 october 29, 2026

“B. de Finetti Risk Seminars – Milano Lectures on the Mathematical Theory of Economics and Finance,” Date and location: October 29, 2026, at 6:00 p.m., in Room C12, Via Mangiagalli 25, Milan. Speaker: Prof. Rudiger Frey (WU, Vienna University)   Title: Focus or Diversification? Dynamic Allocation of Climate-Technology Investment under Budget Constraint Abstract: Decarbonizing electricity production requires …

QFinLab Seminar – Virginia Pugliese (Bank of England)

 october 14, 2026

Tuesday, 20 October 2026, 12.15-13.15Seminar room, third floor, building 14, Via Bonardi 9, Milano (Leonardo Campus); online (Microsoft Teams), Link  Virginia Pugliese (Bank of England) Title: X marks the bank: digitalisation and depositor runs. Abstract: This paper examines how digitalisation amplifies liquidity pressures on banks during periods of financial stress, emphasising the role of social media in …

QFinLab Seminar – Gabriele Sbaiz – 25/5/2026

 may 18, 2026

Monday, 25 May 2026, 13.15 Seminar room, third floor, building 14, Via Bonardi 9, Milano (Leonardo Campus); online (Microsoft Teams), Link Gabriele Sbaiz (University of Trieste) Title: Environmental impact into multi-objective portfolio allocations Abstract: In this talk, we tackle a sustainable multi-objective optimization problem in which we aim to maximize a mean-risk ratio while, at …

QFinLab Seminar – Riccardo Brignone

 april 28, 2026

4/5/2026, 13:15 @ Department of Mathematics, Politecnico di Milano Monday, 4 May 2026, 13.15 Seminar room, third floor, building 14, Via Bonardi 9, Milano (Leonardo Campus); online (Microsoft Teams). Riccardo Brignone (University of Pavia) Pricing path-dependent options under stochastic volatility models with arbitrary accuracy Abstract: We propose a unified methodology for pricing general path-dependent derivatives, …

QFinLab Seminar – Neofytos Rodosthenous (University College London) – 21/4/2026, 15:30 @ Department of Mathematics, Politecnico di Milano

 april 15, 2026

Tuesday, 21 April 2026, 15.30-16.30 Seminar room, third floor, building 14, Via Bonardi 9, Milano (Leonardo Campus); online (Microsoft Teams), Link  Neofytos Rodosthenous (University College London) Title: Regulation in a mean-field investment game with climate damage. Abstract: We develop a mean-field model of firms investing in carbon-intensive (brown) capital, where productivity declines due to temperature-related climate damages linked to cumulative emissions. Firms aim to maximise …

Seminario Fabrizio Lillo in Bicocca

 april 14, 2026

Martedì 14 aprile alle ore 11 presso la Sala del Consiglio al quarto piano dell’edificio U7 della Università di Milano-Bicocca, Fabrizio Lillo terrà un seminario dal titolo Why is the estimation of market impact of large trades with public market data so challenging? Estimating market impact and transaction costs of large trades (metaorders) is a …

Rome Joint Seminars on Stochastic Dynamics, Control, and Learning (RoJo-SDCL)

 april 16, 2026

We are pleased to announce that the second meeting of the Rome Joint Seminars on Stochastic Dynamics, Control, and Learning (RoJo-SDCL) will take place on Thursday, April 16, 2026, from 4:00 PM to 6:00 PM, at the EIEF–World Bank shared building (EIEF – Einaudi Institute for Economics and Finance), Conference Room, Via degli Abruzzi 10, Rome. The speakers …

“Peter Carr” Seminars 

 december 11, 2025

Thursday, December 18, 2025, at 2:30 PM Room III at the Department of Statistical Sciences in Via Belle Arti, 41 or via the Microsoft Teams platform “Betting Around the Clock: Time Change and Long Term Model Risk” Prof. Umberto Cherubini (University of Bologna) Abstract We investigate the performance of the Kelly rule in a setting in …

QFinLab Seminar – Politecnico di Milano – Sergio Pulido (ENSIIE, LaMME)

 december 2, 2025

QFinLab – Department of Mathematics, Politecnico di Milano. Tuesday, 9 December 2025, 12.15-13.15 Seminar room, third floor, building 14, Via Bonardi 9, Milano (Leonardo Campus). Sergio Pulido (ENSIIE, LaMME) Polynomial Volterra processes Recent studies have extended the theory of affine processes to the stochastic Volterra equations framework. In this talk, I will describe how the …

➤